The best answer to how to avoid wedding debt is to set a true all-in spending ceiling before booking, plan from money already saved or firmly promised, keep the guest list intentional, refuse high-interest balances, and cut scope before borrowing. A debt-free wedding is not about making the day feel smaller than your love. It is about protecting the life that begins after the last toast.
Wedding spending gets emotional quickly because every choice seems attached to memory, family expectation, hospitality, or beauty. A venue tour becomes a vision. A floral upgrade starts to feel like proof that the day matters. A guest-list addition sounds kinder than explaining a limit. Then, quietly, the wedding begins asking for money the couple has not actually decided to spend.
Think of this as a calm budgeting framework, not personalized financial advice. The goal is to plan a beautiful wedding without turning the first year of marriage into a repayment plan. For many couples, especially those drawn to a small wedding, the most elegant decision is not the most expensive one. It is the decision that keeps the celebration honest, warm, and possible.

Recommended Wedding Products


You Might Also Like These Blog Posts
- Is A Wedding Worth The Money When You Want Meaning More Than Pressure
- Wedding Mistakes To Avoid If You Want The Day To Feel Like You
- Gen Z Wedding Budget Tips For A Celebration That Still Feels Like You
- What Gen Z Is Really Spending On Weddings And What Actually Feels Worth It
- How To Simplify Wedding Planning Without Making The Day Feel Smaller
- How To Cut A Wedding Guest List To Save Money And Stay Kind
How To Avoid Wedding Debt Without Losing The Meaning Of The Day
The clearest way to avoid wedding debt is to make money decisions before the wedding starts seducing you with specifics. A blank budget feels cold until a real invoice arrives. A guest limit feels awkward until catering is priced per person. A savings timeline feels restrictive until a credit-card balance follows you home from the honeymoon.
Start with the life you want after the wedding. Rent or mortgage payments, savings, health costs, work changes, travel, family support, and ordinary living expenses still exist after the reception. Your wedding budget should fit those realities instead of pretending they pause for one beautiful day. That does not make the wedding less romantic. It gives the celebration a kinder frame.
A debt free wedding usually comes from many steady decisions rather than one dramatic sacrifice. The guest list stays honest. The venue fits the actual budget. Food is priced before decorative extras. Family money is clarified early. Deposits are tracked. Trend-only details are questioned. Credit cards are treated as payment tools, not extra budget. Wedding loan alternatives are considered before borrowing becomes the easy answer.
The most helpful mindset is to treat every wedding decision as part of one shared plan. A dress appointment affects alterations and accessories. A venue affects transportation and rentals. A plated dinner affects service staff and tips. A larger wedding party affects flowers, gifts, beauty timing, and getting-ready space. Debt grows when each choice is approved in isolation, so keep bringing the conversation back to the full picture.
Set A True All-In Budget Before Venue Tours

A wedding budget without debt starts with a complete number, not a hopeful venue number. Decide the most you are willing to spend across the whole wedding before tours, tastings, dress appointments, and floral proposals begin. That number should include venue, food, bar, rentals, attire, beauty, stationery, rings if relevant, transportation, lodging, tips, taxes, delivery fees, gifts, welcome events, rehearsal costs, post-wedding brunch, alterations, permits, weather backup, and a buffer.
The all-in budget matters because debt often hides in the categories couples forget. A venue looks different once service charges, gratuity, rentals, catering minimums, insurance, extra hours, and transportation appear. Write one total at the top of your planning document and make every choice answer to it. If the total has to move, pause and decide together before anyone pays another deposit.
Choose A Debt Rule Together
Before anyone books anything, choose a debt rule that both partners understand. It could be no credit-card balance after the wedding, no personal loan for the wedding, no borrowing without a written payoff date, no spending that drains emergency savings, or no upgrade unless another line is reduced by the same amount. The rule should be plain enough to remember when a vendor is charming and a family member is persuasive.
This conversation is less about restriction than trust. A couple who shares a debt rule does not have to renegotiate every emotional moment from scratch. When one person falls in love with a larger room or a more elaborate menu, the question becomes simple: does this still fit our rule, or are we asking future us to pay for present pressure?
Build The Wedding From Available Cash

Add up current savings set aside for the wedding, monthly contributions available before final payments, and family contributions that are confirmed in writing or unmistakably clear. Keep uncertain gifts, hoped-for bonuses, future overtime, and possible cash gifts out of the base budget. Those amounts could arrive, but they should not be the foundation of signed contracts.
When the available cash number is smaller than the imagined wedding, treat that as useful information rather than failure. Reduce the guest list, choose a different date, simplify the bar, skip extra events, narrow the decor plan, or extend the timeline. The earlier available money shapes the wedding, the more graceful those changes feel.
Make the wedding savings plan visible enough that both partners know where the money is coming from. A shared tracker, separate savings account, or simple monthly check-in keeps the plan from living inside one person’s head. If the savings pace slows, update the wedding before the shortfall becomes a balance.
Extend The Engagement If Saving More Would Reduce Stress
A longer engagement is sometimes the most peaceful wedding loan alternative. If three, six, or twelve more months would let you save without carrying balances, the extra time protects both the wedding and the marriage. More time also gives you a better chance at preferred vendors, less frantic payment deadlines, and calmer decisions.
There is no moral prize for planning quickly while quietly borrowing. If the wedding you want needs more cash than the current timeline allows, decide whether the date or the scope is more flexible. A later celebration you pay for outright is often lighter than an earlier celebration that follows you around in monthly payments.
Cap The Guest List Early
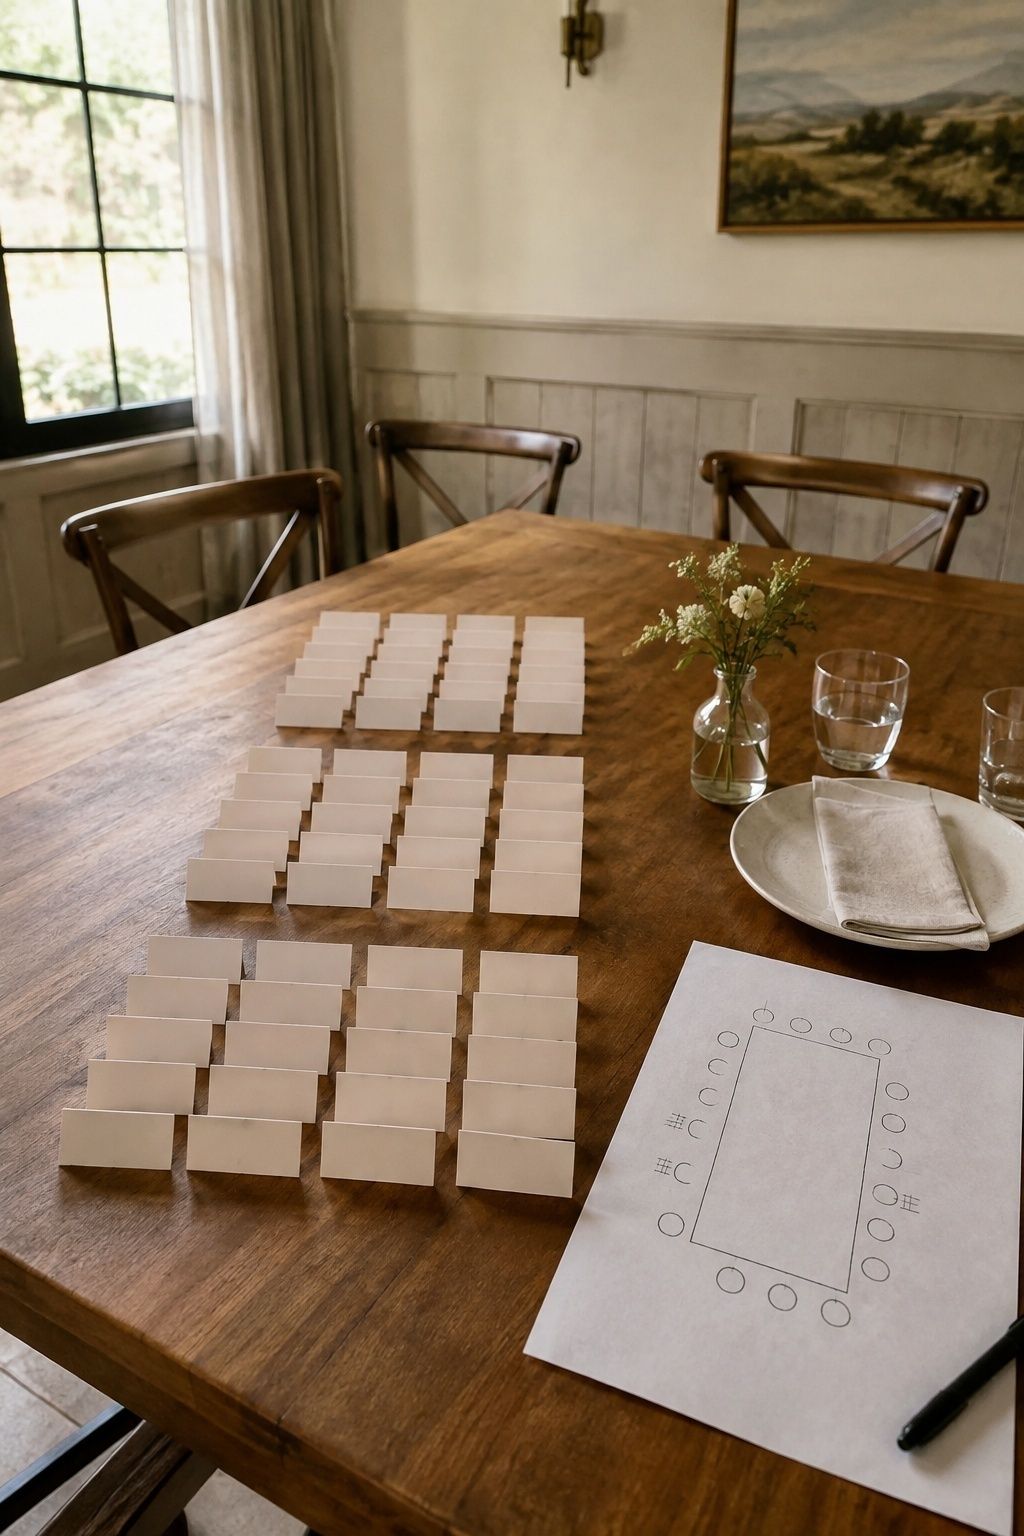
The guest list is not only a social decision. It is a financial engine. Every additional guest affects food, bar, invitations, chairs, place settings, linens, favors, stationery, transportation, venue size, service staff, and sometimes restrooms, parking, setup time, and security. If you want a small wedding debt free, guest count is usually the first lever to protect. It is one of several wedding mistakes to avoid early in planning.
Make a list of the people closest to the marriage, then price that version before expanding. A 30-person dinner has different possibilities than a 120-person reception. A shorter list often leaves room for better food, stronger photography, more comfortable hosting, or a dream ceremony location. Downsizing is not rude when the boundary is clear and consistent.
Price Venue And Food Before Decor
Decor is easy to imagine, but venue and food usually decide whether the budget is stable. Before you buy signs, candles, favors, specialty linens, guest-book displays, or late-night extras, price the room, ceremony setup, catering, bar, service, rentals, fees, gratuity, taxes, and minimums. Those numbers reveal what is truly left.
If venue and food consume most of the budget, simplify the visual plan with confidence. An intimate wedding does not need a crowded design scheme to feel beautiful. Candlelight, seasonal flowers, thoughtful table spacing, one strong color story, and good timing often do more than a pile of extra details bought after the real costs were already known.
Keep A Payment Calendar

Wedding debt sometimes appears at the end because payments were scattered across inboxes, portals, checks, deposits, and verbal reminders. Create one wedding payment tracker with every vendor, total cost, deposit paid, remaining balance, tax, tip, payment method, due date, late fee, and final deadline. Review it weekly as the wedding gets closer.
A payment calendar also prevents double-counting. A balance due in October is not theoretical just because it is not due today. Treat every signed balance as already spent, then plan from what remains. This keeps the final month from becoming a scramble of surprise charges and last-minute credit-card swipes.
Build a small cushion into the tracker for the expenses that arrive late: garment steaming, postage, parking, extra ice, vendor meals, marriage-license fees, rain supplies, delivery charges, and tips. The cushion should not become a secret upgrade fund. It exists so ordinary details do not push the couple toward avoidable borrowing during the last week.
Do Not Finance Social Media Pressure
Some wedding extras look essential only because they photograph well. Outfit changes, oversized signage, elaborate welcome bags, custom dance floors, floral ceilings, champagne towers, content-ready lounges, and highly specific trend moments look lovely, but they should earn their place inside the budget like anything else. A detail that was never part of your priorities should not become wedding credit card debt because it looked irresistible online.
Ask whether the upgrade improves the guest experience, the ceremony, the meal, the comfort of the space, the photographs you truly value, or the emotional memory of the day. If the answer is mostly that it looks impressive to people who will not be there, let it go. Your marriage deserves more protection than a trend cycle.
Ask Family Contributors Clear Questions
Family money should be kind, clear, and usable. Ask whether a contribution is a gift, a reimbursement, a loan, or support tied to specific expectations. Clarify when the money arrives, whether it has to be used for a certain category, whether it affects the guest list, and whether the contributor expects decision-making power.
Do not build contracts around vague promises. A parent saying they will “help with the wedding” is different from a confirmed amount available by a certain date. If family support carries conditions that would push the wedding beyond your debt rule, thank them and decide whether the money is worth the added pressure.
Cut Scope Before You Borrow

When the numbers do not work, reduce the wedding before adding debt. Cut guest count, change the day of the week, choose brunch or lunch instead of a full evening reception, simplify the bar, reduce the wedding party, skip extra paper goods, choose fewer floral moments, remove favors, cancel optional transportation, or keep the celebration to one event instead of a weekend.
Scope cuts feel better when you protect meaning first. Keep ceremony sound clear, make food and timing comfortable, preserve photography that matters to you, maintain weather backup, and care for accessibility. Then let go of the parts that ask for money without giving the day much emotional or practical return.
Use Credit Cards Only With Payoff Money Ready
Credit cards offer convenience, purchase protections, or rewards, but they are risky when the balance will not be paid in full. Interest, fees, high utilization, and future borrowing plans turn a short-term wedding choice into long-term pressure. Treat the card as a payment method only when the payoff money already exists or arrives before interest begins.
If a vendor surcharge applies, include it in the budget before choosing the card. Rewards are rarely worth paying fees or interest. The safest question is not whether the card limit allows the charge. The safer question is whether the charge disappears before it becomes a balance you resent.
Be Careful With Wedding Loans
A wedding loan makes an unaffordable plan look temporarily affordable because it turns one large total into smaller monthly payments. That does not make the wedding less expensive. It moves part of the celebration into married life, with repayment terms, interest, and less flexibility for everything that comes next.
Before borrowing, price the smaller wedding first. Price a later wedding. Price a shorter guest list. Price a restaurant dinner, private room, courthouse ceremony, backyard meal, weekday venue, or no-extra-events version. If the only way the wedding works is through debt, the plan is asking for more than the couple has agreed to give.
Protect Emergency Savings
Emergency savings protect rent, housing, medical needs, job changes, family obligations, transportation, and everyday stability. Emptying that fund for a wedding avoids a loan on paper while creating a different kind of risk. A wedding should not leave the couple one ordinary setback away from panic.
Decide how much emergency money remains untouched before wedding spending begins. If preserving that cushion reduces the wedding budget, accept the honest number. The peace of knowing your real life is protected is part of the celebration, even if guests never see it on the table.
Have A Plan If Debt Already Happened
If balances already exist, pause new spending and write down every amount owed, interest rate, minimum payment, due date, promotional end date, and repayment term. Then separate essential remaining wedding costs from optional ones. The plan is no longer just how to avoid wedding debt. It is how to keep existing debt from growing while you finish the event responsibly.
Some couples choose a payoff order, reduce expenses, sell unused items, add short-term income, or speak with a qualified credit counselor when the debt feels unmanageable. What matters is not pretending the balance will take care of itself. Wedding debt becomes less frightening when it has numbers, dates, and a realistic repayment plan.
Why Small Weddings Help Couples Stay Debt-Free
A small wedding does not automatically create a debt free wedding, but it gives the couple stronger control over the biggest cost drivers. Food, bar, rentals, invitations, favors, stationery, guest transportation, room size, service staff, and setup needs all respond to guest count. With 20, 40, or 60 guests, money has fewer places to leak away unnoticed.
The emotional benefit matters too. A smaller guest list makes it easier to explain boundaries, choose a venue that fits the actual gathering, personalize the meal, and protect the ceremony from becoming a production. Couples often discover that the less they spend on obligation, the more room they have for the parts they remember: a table where everyone talks easily, flowers where they matter, music that feels personal, a photographer who notices the quiet moments, and enough breathing space to enjoy the day.
When people talk about wedding guest list debt, they are usually talking about more than food. They are talking about the cost of not disappointing anyone. A small wedding asks a brave question early: who truly needs to be in the room for this promise? Answering that honestly saves money and also makes the celebration feel more like yours.
What To Cut Before You Cut Meaning
Cut the items that create cost without protecting comfort, memory, or hospitality. Favors, extra signage, premium rental upgrades, duplicate outfits, printed extras, oversized wedding parties, unnecessary transportation, elaborate welcome bags, large floral installations, late-night add-ons, and obligation guests are all worth questioning before the couple borrows.
Protect the parts that make the day work: a clear ceremony, food served at the right time, comfortable seating, weather backup, accessibility, photography that suits the event, honest communication with guests, and a timeline that does not exhaust everyone. A smaller plan with those pieces intact will usually feel more generous than a larger plan funded by stress.
The most graceful wedding budget limits do not say no to beauty. They say yes to the version of beauty the couple actually affords. Choose fewer details and let them be thoughtful. Choose fewer guests and host them well. Choose fewer upgrades and keep the first month of marriage lighter.
If a cut feels painful, ask what feeling you were trying to create. Maybe the floral installation was really about softness, the extra course was really about abundance, or the welcome bags were really about gratitude. Once the feeling is clear, look for a smaller expression: seasonal bud vases, a generous family-style dish, a handwritten welcome line, a candlelit table, or a quieter room where guests feel genuinely cared for.
This is where intimate weddings have a natural advantage. With fewer people, simple choices register more strongly. A carefully chosen menu, a ceremony that sounds personal, comfortable seating, and warm lighting hold the emotional weight that a larger wedding often tries to solve with more production.
FAQ
How do you avoid wedding debt?
You avoid wedding debt by setting an all-in budget before booking, planning from confirmed cash, keeping the guest list intentional, tracking every payment, and cutting scope before borrowing. Decide your debt rule early so credit cards, loans, and family pressure do not quietly expand the plan.
Is it bad to use a credit card for wedding expenses?
Using a credit card is not automatically bad if the payoff money is ready before interest begins and any fee is worth the protection or convenience. Carrying a balance is the risky part. Interest, fees, and credit utilization make the wedding cost more than the original contract.
Should you take out a wedding loan?
A wedding loan should be approached carefully because it moves wedding costs into married life as fixed payments. Before borrowing, price a smaller guest list, a later date, a simpler reception, and fewer extras. If debt still feels tempting, review the repayment terms with qualified financial guidance.
How do you plan a debt-free wedding?
Plan a debt-free wedding by starting with savings, monthly contributions, and confirmed gifts, then building the event around that number. Book the highest-cost items first, track deposits and balances, keep a buffer, and treat every upgrade as a tradeoff rather than a separate decision.
What wedding costs cause the most debt?
The costs most likely to create debt are usually guest-count-driven expenses: venue size, catering, bar, rentals, service, invitations, favors, and transportation. Late upgrades also add pressure. Decor, attire extras, social media trends, and additional events become expensive when they are layered onto a budget already committed elsewhere.
Can a small wedding help you avoid debt?
Yes. A small wedding helps many couples avoid debt because fewer guests reduce many repeating costs at once. Food, bar, seating, rentals, stationery, favors, and venue needs often shrink together. The key is to keep the smaller plan disciplined instead of replacing guest savings with new upgrades.
Final Thoughts
Knowing how to avoid wedding debt gives you permission to plan from steadiness instead of panic. You are allowed to want beauty. You are allowed to host generously. You are also allowed to protect your savings, your sleep, your future home plans, and the first ordinary mornings of marriage.
A debt-free wedding is not a lesser wedding. It is a celebration shaped by honest limits, careful hospitality, and the kind of love that thinks past the reception. Set the ceiling early, keep the guest list close, track payments clearly, and cut scope before borrowing so the day feels both beautiful and kind to the life waiting on the other side.
Before booking anything that would stretch the budget, decide the full amount together and pause if the total no longer fits.
Last update on 2026-10-04 / Affiliate links / Images from Amazon Product Advertising API